Tuesday's French Budget Vote Is Not the Cliff. The Calendar After It Is
Tuesday's Assembly vote is a gauge, not the cliff: last year's equivalent failed 404 to 1 and the budget still passed. On the government's own forecast, the interest bill runs at about €250 million a day in 2027.
Last year, the National Assembly rejected the first part of France's 2026 budget by 404 votes to 1. The budget passed anyway, on Feb. 2, 2026, by Article 49.3, "sans vote des députés sur l'ensemble": no vote by deputies on the whole.
Keep that in mind on Tuesday, Oct. 20, when the Assembly holds a solemn vote on the first part of Prime Minister Sébastien Lecornu's 2027 budget and Fortune calls it a make-or-break moment. It is a gauge. It covers only the revenue half of the bill, and the hazards that can hurt, from Moody's to the ECB to the whole-budget vote, are dated and come after it. Meanwhile the interest bill, which the government puts at €91.2 billion for 2027 (about €250 million a day, by Daybreak Wire's arithmetic), rises on the government's own forecast, because old cheap debt is refinancing at today's rates.
What Tuesday's vote covers, and what it can't kill
The bill was registered on Thursday, Oct. 1. It targets a public deficit of 5.0% of GDP in 2027, against 5.4% expected for 2026, through a government "effort" of €54 billion: about €43 billion of new measures and €11 billion of decisions already taken. Tuesday's vote is on the revenue part only, which includes a lower cap on the retirees' 10% pension tax allowance (from €4,439 to €3,000, worth €1.4 billion).
The revenue part has already been rejected once. On Friday, Oct. 9, the Assembly's finance committee (per the calendar NosParlementaires compiled from Assembly data) voted it down, 31 to 3 with 2 abstentions, and in the chamber debate restarts from the government's text. On Tuesday, Oct. 13, deputies rejected the Socialists' motion to reject the whole budget before debate, 236 to 149. Had the 62 National Rally deputies present voted for it, it would have passed.
So what does a "no" trigger? Less than the headlines imply. Since the 2024 snap election, minority governments have used Article 49.3, the constitutional article that lets a government pass a bill without a vote unless the opposition topples it with a no-confidence motion. The catch is in Reuters' explainer:
"If a no-confidence vote is held and the government defeated following a 49.3, the budget bill would be dropped and the next cabinet forced back to the drawing board."
Reuters, explainer, Oct. 1
Below that, with nothing passed by year-end and no 49.3, a short emergency law could roll over the 2026 budget, which a finance ministry report warned would cause "unprecedented budget paralysis". A budget by ordinance "has never been done in the Fifth Republic", Reuters reports, and experts see a "nuclear option likely to trigger a no-confidence vote".
Each camp has a stated case. An executive source told AFP on Oct. 13 that markets need to feel the deficit will end at 5% whatever happens, and that deputies' debates matter little because everyone assumes a 49.3 or ordinances. Marine Le Pen has said she prefers an adopted budget, even an "imparfait" one, because she believes she could change it deeply if elected president. The Socialists, whose decision not to censure let last year's budget pass, are described as less inclined to do so this year. MUFG's base case is "a somewhat modified version of the budget will eventually be adopted with the government using Article 49.3 to push through parts without a formal vote", and it says Tuesday's vote "will give an indication of how the land lies". An indication is not a verdict.
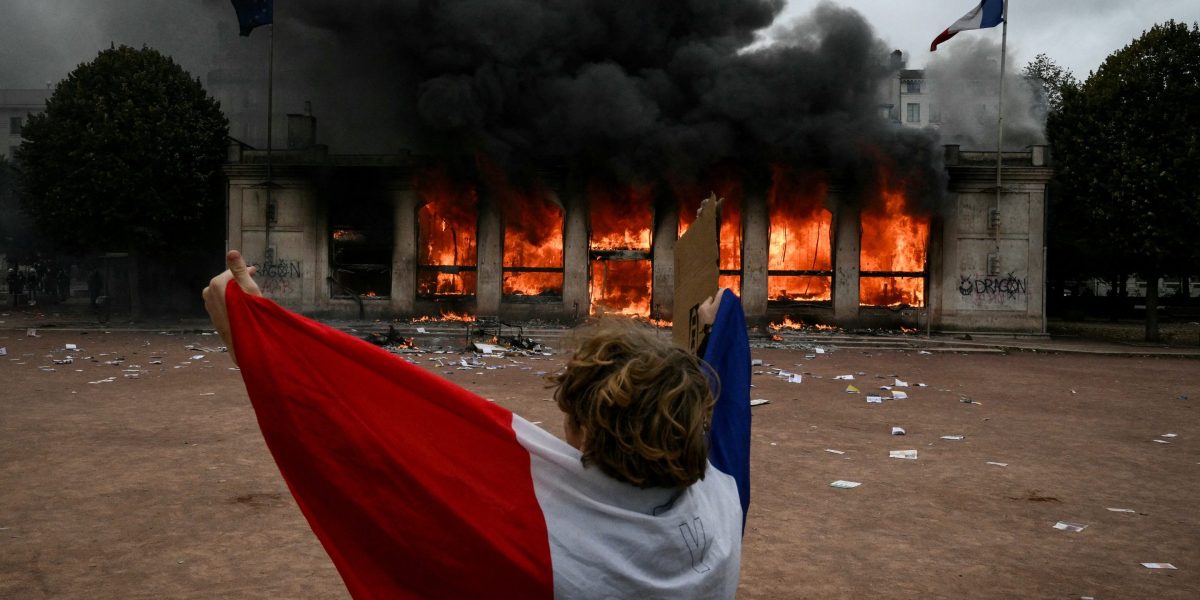
The street complicates that calm. On Saturday, Oct. 17, cost-of-living, school-funding and Yellow Vest protests spread across France. Lecornu said around 1,200 people were arrested and more than 150 police officers injured; Interior Minister Laurent Nuñez said about 550,000 took part, while the CGT union told AFP 800,000. The 272 some outlets ran was an earlier tally in a rising count (the Interior Ministry's preliminary figure was later about 400), not a rival figure. Limoges city hall was set on fire, protesters broke into Marseille city hall, and Lyon's tourism office was set on fire.
Lecornu tied the damage to public money, not to the budget bill. In English translation reported by Yahoo, he said, in connection with a "pay-the-damagers" bill, that public money is scarce: "it must fund our public services, not endlessly repair what vandals destroy."
Post by @SebLecornu
AFP quotes a Macron-camp figure who worried that "si la contestation sociale s'amplifie (...), le RN pourrait la rejoindre": if protest grows, the National Rally could join it by voting to censure.
France now pays more than Italy to borrow
The current yields below are TradingEconomics' quotes for Friday's close, Oct. 16; markets reopen Monday. Its interbank quotes had France's 10-year yield at 4.79%, Italy's at 4.51%, Spain's at 4.05% and Germany's at 3.42%. France's is the OAT, the French 10-year government bond; Germany's is the Bund.
Traders watch the gap to Germany, counted in basis points (100 basis points equal one percentage point). By Daybreak Wire's arithmetic, France's premium over the Bund was 137 basis points, Italy's 109 and Spain's 63. A year earlier, implied by TradingEconomics' 12-month changes, they were about 78, 80 and 53.
Here is what the weekend coverage skipped. A year ago France paid about 2 basis points less than Italy to borrow for 10 years (3.36% against 3.38%). At Friday's close it paid 28 basis points more. Briefs.co reported a record 30 basis points on Oct. 9, the widest since the euro was created.
The high came earlier: on Oct. 1 the OAT rose to 4.96%, "highest levels since 2002", per Il Sole 24 ORE/Radiocor. The doom camp's best line is from Mujtaba Rahman, managing director for Europe at Eurasia Group, quoted by Fortune: "If his government fails to pass the budget, the cost of servicing French debt may explode." The IMF's Mateusz Szczurek, head of the International Monetary Fund's European department, told Reuters on Oct. 16 that the market is orderly and "the short-term debt risks are certainly manageable". As Macquarie's Thierry Wizman, global FX and rates strategist, wrote in a note on Tuesday quoted by Fortune, it would seem that one would have to go through the valley before getting to the other side of the fiscal responsibility gap.
(France sits inside a global rise; see how real rates, not inflation bets, drove the U.S. 10-year yield to a 2002 high.)
The interest line, by household and by day
Interest costs for all levels of government were €64.7 billion in 2025, per Actu Alt Plus. The government forecasts €79.2 billion for 2026 and €91.2 billion for 2027; both are forecasts. By Daybreak Wire's arithmetic, 2025 to 2027 is a rise of €26.5 billion, or 41%.
Divide €91.2 billion by 365 and France pays about €250 million a day in 2027, against €217 million a day in 2026: €32.9 million more every day. Across INSEE's 31.930 million main residences, a fair stand-in for households (Daybreak Wire's own approximation), that is €2,856 a year, or €7.83 a day, against €2,480 and €6.80 in 2026. The €12.0 billion rise comes to €376 per household. These are averages, not a bill anyone receives; the cost arrives through taxes, services and borrowing.
Why does it rise on the government's forecast? Because it is mostly refinancing. Agence France Trésor, the debt agency, plans to raise €340.0 billion of medium- and long-term debt in 2027, against €310.0 billion in 2026 (Actu Alt Plus, citing the agency). The average issuance rate so far in 2026 is 3.55%, against 3.14% in 2025, and tradable debt has an average life of 8 years and 184 days. Each year older, cheaper bonds mature and are replaced at today's prices.
By Daybreak Wire's reading, a budget vote can change how much France borrows and what it pays on new debt. It cannot change the rate on bonds already outstanding. The IMF put it plainly:
"But if yields are going to stay higher for longer, it will put greater pressure on public finances and cost control."
Mateusz Szczurek, head of the International Monetary Fund's European department, to Reuters, Oct. 16
The stock gives that weight. INSEE's quarterly debt release puts public debt at €3,595.5 billion at the end of the second quarter, or 119.0% of GDP, up from 117.5%. The budget projects 121.7% in 2027 even with the plan, and La Clé Publique notes that of about €23 billion of spending restraint outside interest, about €12 billion is absorbed by higher interest costs. Roughly half the belt-tightening is spoken for before it starts.
The dates after Tuesday, and the ECB's closed door
Counting from today, Sunday, Oct. 18, Tuesday is two days away, Moody's five, the ECB 11, the whole-budget vote 30 and S&P 40.
| Date | What happens |
|---|---|
| Tue., Oct. 20 | Assembly's solemn vote on the first (revenue) part of the 2027 budget |
| Fri., Oct. 23 | Moody's scheduled review of France (now Aa3, negative outlook) |
| Tue., Oct. 27 | Assembly vote on the social security budget |
| Thu., Oct. 29 | ECB policy decision and press conference |
| Tue., Nov. 17 | Assembly vote on the whole budget (possibly Nov. 18) |
| Fri., Nov. 27 | S&P scheduled review (now A+, stable) |
| Mid-December | Parliament's deadline; after it, a budget by ordinance becomes possible |
Moody's rates France Aa3 with a negative outlook; S&P and Fitch say A+ with stable outlooks. The Oct. 23 review comes from a UBS report cited by Yahoo Finance and MNI's compilation of the agencies' review calendars; the Nov. 27 S&P date is on that calendar only, so treat it as scheduled. Agencies can act outside a calendar, and nothing here predicts what they will do. The last date is soft: the Constitution gives Parliament until Dec. 17, and AFP puts the earliest ordinance date at Dec. 18.
Will the ECB ride to the rescue? Its president's latest words were about tighter financing conditions across the euro area, and she did not mention France. On Saturday, Oct. 17, Christine Lagarde said, per Reuters: While growth has been resilient, financing conditions have tightened, with long-term interest rates rising notably since our last meeting.
It does have a tool. Reuters' explainer describes the Transmission Protection Instrument, which lets the ECB buy unlimited bonds of a country facing "unwarranted, disorderly" tightening. It has never been used. France is under an EU excessive deficit procedure, and spreads rose "by relatively measured increments", so "it is also hard to show it is disorderly". The next decision is Thursday, Oct. 29.
For ordinary money, borrowers feel it first, with a lag. Pretto's October averages are 3.53% over 15 years, 3.65% over 20 and 3.8% over 25. Pretto's explanation: when the State pays more to borrow, banks do too, and "tôt ou tard" pass it on. In illustrative arithmetic, not a bank quote, a €200,000, 20-year loan costs about €1,175 a month at 3.65%, against €1,164 at the early-September 3.54%. (How bond moves reach loan rates: the Fed talk that moves mortgages.)
Savers sit on the other side of the trade. Boursorama says euro funds, the capital-guaranteed fund inside a life-insurance contract, averaged 2.60% for three years and could reach about 2.9% in 2026 as insurers invest new money at higher yields. Elsewhere in the euro area, Reuters reported on Oct. 1 that Italy's spread rose to 110 basis points, Greece's to 95 and Belgium's to 80.
Whichever way the red consoles light up on Tuesday, the government's own forecast has the meter running at about €250 million a day in 2027. Moody's looks at France on Friday.